Showing posts with label mutual fund. Show all posts

Thursday, December 19, 2019

The 401K Diversification Article You MUST Read Today

My earlier Portfolio Diversification – 401K article provides an in-depth example of designing a diversified portfolio. I would urge everyone to read this previous comprehensive article today. It covers:
  • MPT (Modern Portfolio Theory)
  • Typical funds in corporate 401K plans
  • Hard truths about size
  • Active funds vrs. index funds
  • Fund selection
  • Risk Tolerance
  • Portfolios by Age and Risk Tolerance
  • Re-balancing
  • 401k and Diversification Resources

How has my 401K performed?

It has been over a decade since the 401K Portfolio Diversification post; in this time I have regularly re-balanced the 401k account and adjusted it as my age increased.   My 401K has performed in-line with the the market indexes and expectations. In areas where active funds were used rather than index funds; actively-managed Small Cap Funds (SSMVX and successors) have out performed the indexes. Actively-managed Bond Funds and Foreign Stock funds generally have under-performed their indexes.  The under-performance of Bond funds was impacted by the low interest rate environment.

I stuck with my 401K portfolio and am generally pleased with the results over time.

Saturday, December 14, 2019

In Retrospective - 130/30 Funds

Back in 2007, 130/30 Funds were hyped as the next great thing in the market. As the market tumbled a dozen years ago the concept of a fund that would generate profits in both rising and falling markets was a sales pitch that hit appealed to the pain investors were encountering at this time.

Multiple mutual fund families immediately offered 130/30 Funds mirroring hedge funds. The mutual funds launched marketing campaigns in 2007 worked to draw in investors based on downside fear - many remembering the 2000/2001 decline. Some ads implied investors would profit greatly in both rising and falling markets.

As outlined earlier, 130/30 funds allow managers to short-sell up to 30% of their portfolios, and use the proceeds to buy an extra 30% long. The funds both use leverage and short-selling.

Now over a decade later - how have 130/30 Funds fared?   Back at that time I was very skeptical of 130/30 Funds. The results demonstrate I was quite right to question these 130/30 Funds as nothing more than a marketing gimmick with the intent of generating out sized fees for financial institutions.

Since 2008 the financial press has covered the decline of 130/30 Funds.   However now in 2019 as we seem to be approaching a market peak new 130/30 Funds are now again being offered.  One example is JPM and UBS unveil 130/30 funds.

A long list of media has demonstrated the gimmicks and decline of 130/30 Funds as they greatly under-performed the related index put forward by Andrew Lo of the Massachusetts Institute of Technology and Pankaj Patel of Credit Suisse and merely served as a payday for money managers.  A sampling of media 130/30 Fund articles include:

The decline, fall and afterlife of 130/30
https://www.ft.com/content/fdbf6284-b724-11e2-841e-00144feabdc0

130/30 Funds: 130% Gimmick/30% Good Idea
https://www.morningstar.com/articles/287506/13030-funds-130-gimmick30-good-ideak/30% Good Idea

130/30 Mutual Funds: Don’t Believe the Hype
https://investorsolutions.com/2012/09/28/13030-mutual-funds-dont-believe-the-hype-3/

A Hot Fund Design Turns Cold
https://www.wsj.com/articles/SB10001424052748704388504575419642095323262


Now that 130/30 Funds are being pushed by brokerages again, don't fall for the hype. Stick with your long term investment plan with proper diversification, low fees, and a long term view.


Friday, December 13, 2019

How to get Rich in the Stock Market

There has been all sorts of media, companies and individuals pushing methods of "getting rich in the stock market".  The proposed strategies range from stock picking to trading, all the way out to using esoteric long/short hedging strategies with options & futures.

The reality is that there is only one guaranteed method to get rich in the stock market. It involves time, diversification, low-cost funds, continuous investment, and patience.

1) Time
The first factor is time; you will need to be focused on the long term.  Success in the stock market is not based on the next quarter or year, but the expectation for results over long periods of time akin to decades.

2) Diversification
It is important to be properly diversified based on your investment objectives, accepted risk tolerance, and time frames.  You should be diversified across domestic stocks, international stocks, growth/income, and company size.  The is also need for a balance between stocks, bonds, and other investments based on your age and objectives. There are many articles available that discuss proper diversification including - Why Diversification Is Important in Investing.

My earlier thoughts on 401K diversification can be found here - https://www.gregboop.com/2007/02/portfolio-diversification-401k.html

3) Low-cost Funds
Investment costs such as mutual fund fees can eat into a good portion of your returns over time.  Funds with high fees don't offer better returns over time than index funds -- in fact many times their returns are worse than index funds.  It is best to find mutual funds that mirror indexes offered from funds families such an Vanguard, Fidelity, and Schwab. Mutual Fund marketing fees, front end load fees, back end load fee and other assorted fees merely make financial people rich -- they don't help you are all. 

4) Continuous Investment
The market goes through many cycles.  By investing regularly - for example adding money each paycheck to a 401K or IRA - you are riding the cycle.  When the market pulls back you are buying more at lower cost; when the market rises you are making solid returns on what you have purchased over time.   Continuous investment provides a safety cushion for market cycles; it is a much better strategy than simply purchasing funds at one point in time.   If you buy at the peak with all of your cash it is a harder climb to get solid investment returns.

5) Patience
Be willing to hold on an ride out market cycles.  Do not panic when the market goes down.  Do not take a lot of money out simply because the market is up (trying to time the market).  You need to have a long term view and be patient.  Getting "rich" in the stock market is a long term "play" not something that happens by next year.

Wednesday, July 2, 2008

Circuit City: So Toxic that Nobody Wants It

Is there such a thing as a bride so ugly that no one will marry her? Apparently there is such a thing as a business so toxic that everyone steps away from buying it.

One of the great fears of any party seeking to close a deal to purchase Circuit City (CC) is that the due diligence would reveal information so negative that potential acquirers would drop their bids. Apparently this scenario is playing out.

Blockbuster (BBI) dropping its bid may be due to other bidders pushing up the price; more likely it is that further disclosure revealed that Circuit City is already deeply entangled in its death throes. Blockbuster's Chief Executive Jim Keyes cited "market conditions" as a reason for withdrawing its offer, valued at up to $1.3 billion, and said the deal was not in the best interests of its shareholders.

Circuit City dropped over 16% on the open on Wednesday after this news. Blockbuster climbed over 12%, the shareholders gleeful that this proposed merger has been dropped. It is interesting to note that Blockbuster had offered at lest $6 per share for Circuit City. CC stock now sits at $2.19; effectively the proposed deal was at triple the price of Circuit City stock. The failure of Circuit City management to grease the skids on this deal will probably go down in financial history as one of the worst executive decisions ever; unless some other suitor actively closes on a transaction.

Philip J. Schoonover, the CEO of Circuit City, kept hope alive for a deal by commenting, "Our exploration of strategic alternatives is intended to serve the interests of our shareholders by considering every possible alternative to enhance shareholder value. The board's review was not dependent on Blockbuster's (BBI) participation. We are diligently working with the parties involved in the process, and intend to continue our thorough approach until such point as the board determines upon a particular strategic course of action. The board has not established a deadline for completing the review."

Loosely translated this means, “We are trying to find a deal that will leave the existing management team employed with large compensation packages despite our ruinous track record. The board is hoping some magical deal materializes shortly with a private equity fund. If something does not pop up soon; the company will be dead as we complete the review of the bankruptcy paperwork.”

The only constant is that the long suffering Circuit City stockholders will continue to be disappointed.

Tuesday, June 17, 2008

How come Mutual Fund Managers don’t invest in their own funds?

Once again, an article highlights that the majority of mutual fund managers avoid their own funds. Why would a customer want to buy fund when the manager won’t touch it?

Maybe the manager knows that the expense fees in most mutual funds eat you alive over time, and most knowledgeable investors are better off investing directly in stocks. John Bogle, the former chairman of Vanguard group, talks about this trend in his discussion about the “The Battle for the Soul of Capitalism”.

Morningstar reported that 47% of the managers of U.S. stock funds reported no ownership in their own funds. 61% of the managers of foreign stock funds and 66% of taxable bond funds do not own their funds. Similarly 71% of the managers of balanced funds will not include the funds in their holdings.

Do they know the funds are so toxic or poorly run that these managers will not even pick up a small number of fund shares – maybe this would be a good display of confidence.

Once again this is a dismal reflection of the mutual fund industry, and demonstrates that many managers do not believe their “gimmicky market-driven funds” are designed for the long haul. Investors should focus on low fees when investing in mutual funds and take a look if the manager actually holds shares.

Thursday, May 15, 2008

Four Out of Five Wrong

Morningstar touts its own services in a recent How to Find Bargains in Today's Market that outlines “5 Ways to Spot Cheap Securities”. So what is the problem? Four of the five points are absolutely wrong and will only help investors under-perform the market. Let’s take a closer look at the five assertions and why investors should never “follow these points to the letter”.

1) Home in on cheap stocks

“Find those companies that are trading at well below the prices that our equity analyst team thinks they're worth.” The majority of these companies are trading at a discount for a reason; the firms are suffering from industry challenges, mismanagement, or other significant headwinds. Statistically 70% of these companies under-perform over the upcoming 2 and 5 year periods. Just because a company trades at a discount to theoretical value does not mean it is a good investment, in fact many are absolutely horrible.

2) Identify index mutual funds and exchange-traded funds that hold cheap stocks

Remember how well this strategy worked from 1997 to 2001. There are many other time periods where “value” under-performed. Many times an index mutual fund or ETF holding stocks that are selected simply because of their cheap valuation are merely holding a basket of market under-performers. While it is important to consider low expenses in your fund selection, any focus on “cheap” underlying stocks over the potential of the holdings is misguided.

To the second sub-point, many times ETFs and mutual funds trade at a discount to their associated index. Many times this situation continues for years. Knowledgeable investors look for changes from the historical statistical mean of the standard discount as a signal to buy or sell; they do not simply purchase an ETF or fund because it is selling at a discount.

3) Check out newly reopened funds

Usually the reason that funds are re-opened is because they have horribly under-performed and thousands of investors have fled with their cash. Usually these funds are also sizeable meaning it will be hard to correct their course moving forward.

The concept that investors should hunt for reopened funds is dreadful advice. Generally only actively managed funds which do not have a large amount of assets outperform the market. Investors would be better searching for funds with good managers that are not large in size (in terms of total assets).

4) Investigate target-date funds

Target-date funds are designed to allow large mutual fund families to double dip. First they get fees from the under-lying fund and then from the “target-date” fund. Multiple write-ups have called these funds a “pyramid of fees” that are bad for investors.

Investors are better off to understand basic portfolio diversification, and select a set of low-expense funds that meet their needs. Utilizing target-date funds is just asking to be socked with higher expenses.

5) Consider tax-managed funds

There is some benefit to tax-managed funds so this point is not entirely off-course. However many would argue that it is more important to focus on performance over tax-savings in your investing; coupled with the reality that many holdings are kept in tax-free accounts such as 401Ks and IRAs.

Summary

Morningstar comes across as trying to create an article that is merely designed to tout their service offerings. Not that the information services that Morningstar provides are bad, I use them myself for both stock and mutual fund research. Unfortunately most of this pitch is laced with advice that should not be heeded by investors. This serves as a typical example that many articles in the financial press are just simply veiled marketing ploys for services or financial products, and the advice given is not always in your best interest. As always, buyer beware.

Monday, March 10, 2008

What is the cost to beat the market?

Every investor wants to beat the market. Many are willing to spend quite a bit extra in fees, expenses, commissions, and other costs in an attempt to squeeze excess alpha out of Wall Street.

A study, “The Cost of Active Investing”, by Kenneth French, of Fama-French fame, has drawn attention to the price paid by average investors as they attempt to beat the market. What is the total cost? Currently, investors spend for than $100B per year attempting to exceed the returns of a standard low-expense index fund.

A recent NYT article outlined the highlights of the study and associated conclusions. Over time the portion of stocks’ aggregate market capitalization spent on trying to beat the market has stayed near 0.67 percent, demonstrating that the financial industry has continued to find ways to fleece investors over time. Even in a changing environment of reduced transactions costs, reduced sales charges, narrowing spreads, and other beneficial factors – the brokerage firms have found new ways to stick it to normal investors.

Sadly, most actively-managed mutual funds fail to beat the market over time. So in one sense, despite the excess costs burdening investors, non-passive investing normally fails to deliver on the promise to wring alpha out of the market for the average investor.

What is the bottom line? Most average investors would be better off placing their money in low-expense index funds. The fees, loads, and commissions charged by actively managed mutual funds rob investors of more than they gain from the active management over time. It is more important for most investors to think about low-expenses than out-performing the market when creating their diversified portfolio.

One other conclusion not touched on in the article is that only active investors who pay close daily attention to the markets are normally successful in squeezing out excess alpha. Most invest directly in stocks and ETFs rather than mutual funds in order to beat the returns offered by index funds. As a whole, these active investors are more successful than most fund managers over time. Typically these information savvy “power investors” focus on value or momentum for their investment decisions, and utilize advanced computer screening tools that enable them to succeed.

Friday, February 29, 2008

Do Mutual Fund outflows spell the market bottom?

Many times ordinary investors are the last to jump on the bandwagon… this is why Wall Street refers to them as “the herd”. Usually these investors are the last to the door after all the professionals and active investors have already established positions.

Mutual Funds are a good representative vehicle of this unsophisticated investor population. The outflows from U.S. equity Mutual Funds in January appear to demonstrate that these investors panicked and headed for the exit door. Over $432.9 billlion was pulled out of equity funds in January, the worst month of outflows since July 2002. In 2002, this month basically marked the bottom of the market with the S&P at 797.70 on July 23, 2002. These lows were re-tested in October of 2002, before the market took off in 2003.

This leads to the question if this behavior once again acts as a signal of a market bottom… or if this is just the start of a severe redemption cycle leading to “cardiac arrest” for the stock market.
Mutual funds markets face long-term outflows

Sunday, February 10, 2008

Will 130/30 Funds hold water?

As pointed out in a recent article in Investment Dealers' Digest, 130/30 Strategies are Set to Gain Traction. Hedge funds and major brokerages have been heavily marketing these funds to institutions such as pension funds. The recent tumble in stocks has only increased the marketing blitz and associated claims that these strategies will squeeze out excess alpha in both down and up markets.

As outlined earlier, 130/30 funds allow managers to short-sell up to 30% of their portfolios, and use the proceeds to buy an extra 30% long. The funds both use leverage and short-selling. The current market size is estimated to be $50 billion, many analysts expect the funds in 130/30 products to grow to $1 trillion over the next few years. However it is an open question if these funds actually can deliver on their promises, or are simply a scheme to increase the fees generated for brokerages and hedge funds.

The usual sales pitch involves presenting quantitative back-tested models and presenting results to investors which demonstrate the increased alpha. Naturally these models have the advantage that the managers can easily tweak the selection criteria to provide the results desired over the time frame. The sub-prime CDO fiasco should provide ample evidence that “quant” models that work in back-testing can easily blow up when applied to a real market. The 130/30 models used by fund managers face a similar risk of immediate under-performance.

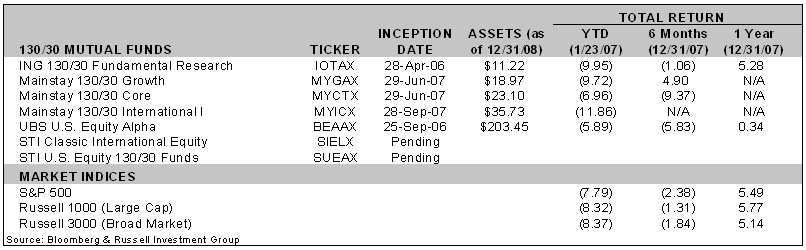
The stock market performance in January was dismal, NASDAQ was down by over 9.9% and other indexes also suffered significant declines. Most people would assume that the performance of 130/30 funds would shine in this type of environment, and many would be near the top of performance lists. The reality is that the performance of the 130/30 funds in January was effectively lackluster in squeezing excess alpha out of the market. There is no data that demonstrates any type of significant advantage in the market when all the factors are taken into consideration. In fact, the results from publicly available mutual funds with 130/30 strategies show that they have underperformed the indexes as outlined in Verdict Still Out on 130/30 Leveraged Funds at TheStreet.com (a performance table is provided here). This can hardly be considered “squeezing excess alpha out of the market”.

Most institutions would have been better off allocating a portion of their money to short funds while placing the majority of their funds (80%+) in long opportunities; if they wanted to achieve better performance with lower fees. Veryan Allen touches on some of these issues in his 130/30 overview. Most investors would be better sticking to traditional products than using 130/30 funds according to Morningstar.

A number of industry specialists would state that 130/30 funds simply limits the long side returns while holding the fund steady in down markets. Another significant issue is that the fees charged for these vehicles are often over-sized compared to other types of funds that institutions can use to achieve comparable exposure. Obviously, a race is on by large financial services firms to acquire more institutional assets in this down market. The 130/30 funds serve as a compelling story, and also deliver out-sized fees to the large financial institutions. One industry quip stated that the collection of fees for a 130/30 fund are usually 0.53% greater than the combination of simply buying equivalent long and short funds. Pension & Investments Online states that a pension fund typically pays 50 to 75 basis points for an active U.S. large-cap strategy, it pays about 25 basis points more for a 130/30 strategy. PIonline views that 130/30 strategy funds are simply a payday for money managers.

Another industry issue is that long managers simply don’t have shorting experience. Some funds will attempt to bring in money managers on board with this type of experience while others will just pick stocks they view as weak as their short candidates. Simply picking the bottom 10% of screens means that many times the manager is selecting the 10% anticipating a rebound; due to their lack of understanding of the criteria that should define a short candidate near the price peaks rather than troughs. For example, the majority of basic fund screening and ranking strategies would have money managers shorting banks now (when they are likely near their bottom) rather than mid-2007 (when they desperately deserved to be shorted). As outlined in the IDD article, "Shorting is a rare talent to begin with, and it's hard to consistently profit on the short side," says Chris Wolf, managing partner at San Francisco-based funds-of-funds Cogo Wolf.’ It is doubtful that very many of these funds will exceed the 130/30 index defined by Andrew Lo at MIT.

An additional concern is “negative carry”, this is the spread in the borrowing cost required to put on the combination of long and short positions. This cost of leverage immediately creates a negative alpha that the fund must overcome to even arrive at par performance. Thomas Kirchner, the manager of the Pennsylvania Avenue Event-Driven Fund (PAEDX), provides an excellent explanation of this issue in his Negative Alpha is Built Into 130/30 Funds commentary.

In some of the cases, the interest on the combined long-short position goes directly back to the sponsoring institution; the large financial services firms are apt to view this as simply another revenue stream and use it as a mechanism to squeeze extra money out of investors. Nor are the disclosure documents very clear on the size of the payments. This entire situation is definitely self-serving and effectively acts as yet another fee targeting customers.

The combination of high fees, minimal short-selling managerial experience, and interest costs are likely to doom 130/30 funds to be underperforming entities. Certainly the marketing blitz from large financial services entities will drive these funds into institutional holdings such as pensions. However individual investor should avoid these funds, and seek other alternatives to create a properly diversified portfolio that can deliver respectable returns over time in both up and down market conditions.

Thursday, January 10, 2008

Will 130-30 Funds take flight?

The interest in 130-30 fund concept continues to grow. Many mutual fund families have added 130-30 funds to their portfolio over the past year.

The “130-30” funds allow managers to short-sell up to 30% of their portfolios, and use the proceeds to buy an extra 30% long. The funds both use leverage and short, attributes which are usually embraced in hedge fund products rather than mutual fund offerings.

Conceptually the fund manager would go long strong stocks while shorting weaker stocks. The expectation is the mutual fund would outperform the market and generate excess alpha for investors. Other possible strategies include merger and instrument arbitrage. One of the concerns raised is how would the industry benchmark the performance of this type of fund.

A recent paper, by Andrew Lo of the Massachusetts Institute of Technology and Pankaj Patel of Credit Suisse, puts forward a proposed 130-30 index. The index uses a number of fundamental and momentum factors to access stocks. Those with the best scores are included in the index as longs and those with the weakest scores as shorts. The research defines a “dynamic bench-mark consisting of a plain-vanilla" 130/30 strategy”.

Note the HingeFire stock screener is excellent tool for identifying stocks utilizing the fundamental and technical criteria used in the type of model outlined in this paper. The model uses fundamental criteria such as P/E, P/S, and P/B as well as technical criteria such as Money Flow, MACD, and RSI. The HingeFire stock screener is one of the few products that offers a full complement of fundamental and technical indicators.

Naturally there are questions whether the type of mechanical approach proposed in the “130/30: The New Long-Only” paper actually represents a valuable index, or is simply another stock picking strategy. This leads to immediate questions about the value of comparing the returns of any particular 130-30 mutual fund against this index. There is an expectation that the market will either accept or reject the dynamic index model over time as the new 130-30 funds become more popular.

Friday, November 9, 2007

Lifecycle that makes sense

Many savvy financial experts are hesitant to recommend lifecycle or target-date funds because many are just a pyramid of fees; burdening the investor with the expenses of both the underlying funds and additional fees for the management of the life-cycle fund. These funds come across to many as just another way for fund families to increase their revenue. Coupled with the reality that very few of these funds outperform their associated indexes, most investors would be better off managing their own diversification.

The crux of the problem is the expenses; automatic lifecycle as a concept works if the fees can be reduced. Fortunately there are a number of ETFs now offered that provide expenses that are typical less then half of most life cycle funds in the market. Target date funds are popular conceptual with investors simply because you can “set & forget”; the advent of life-cycle ETFs are likely to enhance their broad acceptance with the probable added benefit of driving many large mutual fund families to reduce their fees for these vehicles.

TD Ameritrade and XShares have launched five new target-date ETFs; TDAX Independence 2010 ETF (TDD), TDAX Independence 2020 ETF (TDH), TDAX Independence 2030 ETF (TDN) and TDAX Independence 2040 ETF (TDV) and TDAX In-Target ETF (TDX). These target-date ETFs have expense ratios of 0.65%, compared with about 1.3% for the average comparable mutual fund, Other ETF underwriters plan to offer other lifecycle choices shortly, many of these will have even lower expense ratios.

The recent round of pension reform, in which QDIAs were defined by the U.S. Department of Labor, will place lifecycle offerings as the default investments in numerous 401K plans. Many of these retirement plans will likely start considering the ETF lifecycle products as employees clamor for lower fees.

New ETFs Target Retirement Market
http://finance.yahoo.com/focus-retirement/article/103739/New-ETFs-Target-Retirement-Market?mod=retirement-401k